Imagine a CMO walking into the boardroom with a budget request and a set of numbers the board has never seen before. A director asks why brand spend increased while revenue did not move in the same period. Another asks what happens if the budget is cut by 15%. The CMO cannot answer either question clearly. The argument is already in trouble.
A cmo budget defence board conversation is not really won in the meeting itself. Marketing budgets are defended through months of agreed measures, visible forecasts, regular actual-versus-plan reporting, and a clear record of what different levels of investment are expected to produce. By the time the annual budget meeting arrives, the board should already recognise the numbers and understand what the marketing budget is funding.
There are six steps to make that happen, and only the final step happens in the meeting.
Why budget defences fail
Most budget defences fail before the CMO enters the room.
The first problem is unfamiliar numbers. If the board sees a new marketing dashboard every budget cycle, it has no baseline for judging performance. The second is an inconsistent story. If the explanation for weak results changes every quarter, confidence falls quickly.
The third problem is forecasting. A CMO who never commits to expected outcomes gives the board nothing against which to judge performance. Forecasting does not need to be perfect, but it needs to be visible and honest.
The fourth problem is asking for money to protect activity rather than an outcome. “We need this budget to maintain campaigns” is a weaker argument than explaining what happens to revenue, pipeline, customer demand, brand health or risk when that investment changes.
The solution is not a better presentation. It is a better process that starts months before the budget meeting.
Step 1, agree the scorecard before you need it
Start by agreeing what the board will use to judge marketing performance.
Do this in writing and do it before the budget cycle becomes urgent. The CMO, CFO and relevant executive stakeholders should agree the handful of measures that will appear repeatedly in board reporting.
These might include revenue contribution, qualified pipeline, customer acquisition economics, retention, brand health, forecast accuracy or another set of measures appropriate to the business model.
The important point is familiarity. The board should see the same core measures throughout the year, not discover a new definition of success when the CMO asks for next year’s budget.
If the business already has a separate CMO scorecard, use it rather than rebuilding the measurement system here. Link to the CMO scorecard article from this section.
The practical test is simple: could a director look at the previous three board packs and understand whether marketing is ahead, behind or broadly on plan?
If not, fix that before budget season.
You cannot defend yourself against a target that was created after the fact.
Step 2, build a forecast the board can check
The next step is to make a commitment the board can evaluate.
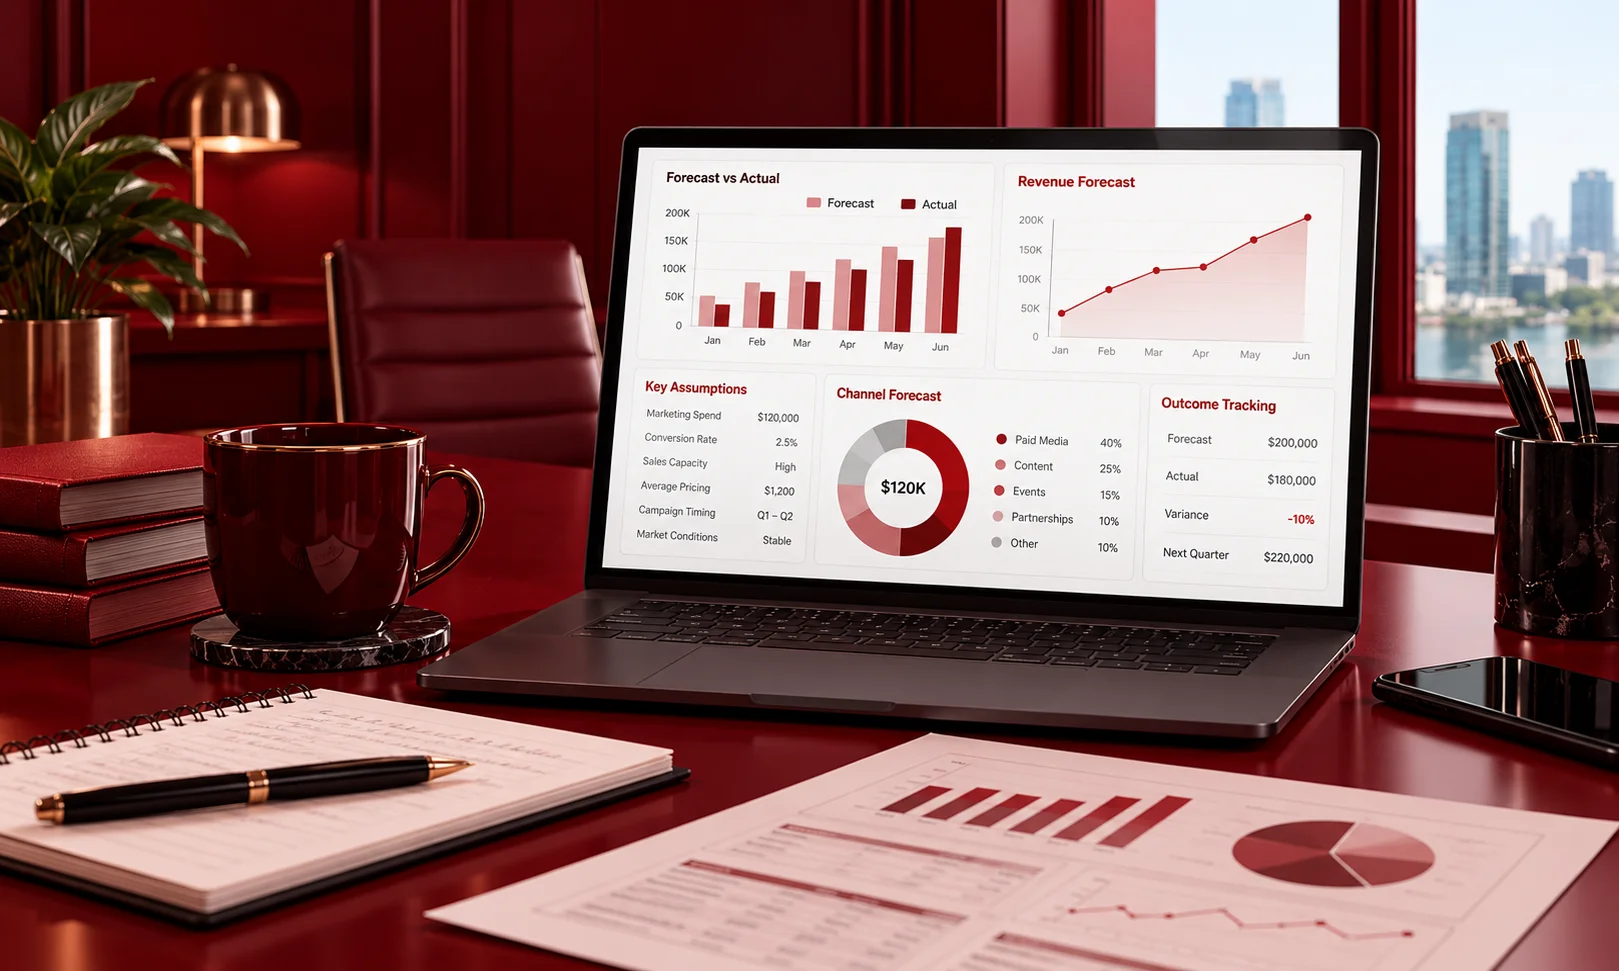
Choose a small number of outcomes and forecast them. Write down the assumptions behind the forecast: expected spend, conversion rates, sales capacity, pricing, campaign timing, market conditions and any other factors that materially affect the result.
Then report against the forecast throughout the year.
If the forecast lands, show it. If it misses, show that too. Explain what changed and whether the change affects the next forecast.
This matters because credibility does not come from predicting everything perfectly. It comes from creating a track record that people can evaluate.
A CMO who has repeatedly forecast results, reported actual performance and explained the gaps gives the board evidence about how marketing planning works in practice. That record becomes part of the case for proving marketing value.
It also makes the budget conversation less abstract. Instead of saying, “We believe this investment will help growth,” the CMO can show what was forecast, what happened, what was learned and what the next investment is expected to change.
If a forecast was wrong, acknowledge it. Avoiding an incorrect forecast may feel safer in the short term, but repeated transparent corrections can create more credibility than never making a measurable commitment.
Step 3, translate the work into the board’s language
Boards are generally trying to understand four things when they examine a major budget: revenue, margin, cash and risk.
That does not mean every marketing activity has to be forced into a fake financial attribution model. It means the CMO should explain why the activity matters in business terms.
This also answers a common question: What marketing metrics do boards care about? Usually, they care less about activity and more about what that activity means for the economics and future position of the business.
Leave reach, impressions, engagement rate and awards out of the centre of the argument unless they directly support a business question.
Consider two translations.
Performance example: Instead of reporting that a paid search programme generated 2.4 million impressions and a 4.8% click-through rate, show that it generated £X in qualified pipeline at £Y acquisition cost, compared with the agreed target. Then explain what additional investment is expected to produce.
Brand example: Instead of claiming that a brand campaign “generated £10 million in revenue”, show changes in brand tracking, consideration or relevant category entry points alongside commercial indicators. Explain that long-term brand work is intended to improve future demand and reduce the risk of becoming less salient, rather than pretending every effect can be attributed to one campaign.
The translation is not about making marketing look more financial than it is. It is about making the business consequence clear.
Step 4, keep the long-term work visible all year
Long-term marketing becomes difficult to defend when the board only hears about it during budget season.
Keep it visible throughout the year.
That can include regular brand tracking, changes in important category entry points, share of voice, consideration, preference, availability and other long-term indicators that make sense for the category.
The key is to explain what slow-moving metrics mean. A flat brand-equity measure may not indicate failure. It may show that an established position is being maintained in a difficult market. Likewise, an improvement may take time to translate into commercial results.
This is where long term brand building needs disciplined reporting rather than a vague promise about the future.
A useful board update can show three things: where the metric is now, what direction it is moving in and why management believes the movement matters commercially.
That creates continuity in board level reporting.
The rule is simple:
A metric that only appears at budget time looks invented at budget time.
If brand investment is important, the board should already have seen its indicators in February, May and August before the annual budget conversation arrives.
Link this section to relevant brand strategy posts and effectiveness posts so readers can explore the measurement and strategic context separately.
Step 5, prepare the cut scenario before anyone asks for it
Do not wait for the CFO to say, “We need marketing to find another 10%.”
Prepare the answer before the meeting.
Build three or four budget scenarios. For example:
| Budget scenario | What changes | What is protected | Expected consequence |
| Full plan | All agreed programmes continue | Growth and brand priorities | Plan remains achievable |
| -10% | Lower-priority activity removed | Core demand and brand programmes | Some targets become harder to achieve |
| -20% | Campaign frequency and selected programmes reduced | Highest-value channels and strategic markets | Slower growth or weaker future demand |
| -30% | Significant programmes stopped | Critical commercial activity | Material increase in commercial and brand risk |
The exact percentages should reflect your business rather than becoming a standard template.
For each scenario, document four things: what gets removed, what gets protected, what changes as a result and when that effect is likely to appear.
This is how a CMO should respond to a budget cut request. Do not simply say no. Show the trade-offs.
A 15% cut may save cash immediately, but the consequences might appear later through reduced pipeline, weaker market presence, higher acquisition costs or slower brand growth. Some effects may be visible within weeks; others may take quarters.
This changes the conversation from “Why won’t marketing accept the cut?” to “Which consequences are we prepared to accept?”
The CMO is no longer defending an arbitrary number. They are explaining the consequences of different choices.
Step 6, the meeting itself
The meeting can be simpler than most CMOs expect.
Use the format:
One page. Three numbers. One ask.
The one-page summary should show the agreed business objective, current performance against forecast, the proposed budget and the consequence of the decision. The appendix can contain channel-level detail, campaign performance, methodology, assumptions, brand tracking and supporting analysis.
The three numbers should be the numbers that best explain the decision. For example: current performance against target, expected outcome from the proposed investment, and the consequence of the cut scenario.
Do not make the board search for the ask. State exactly what is being requested and why.
Before walking into the room, read the finance pack. Know the company’s revenue position, margin pressure, cash position, forecast changes and other investment requests. A marketing budget does not exist in isolation.
If a finance question comes up and you cannot answer it, say so clearly. Do not improvise a number. Explain what you know, what you need to verify and give a specific date when you will provide the answer.
That is more useful than a confident answer that later proves wrong.
The mistakes that lose the room
Defensiveness: Treating every challenge as an attack turns a business discussion into an argument. Instead, acknowledge the concern and connect it to the relevant number or trade-off.
Jargon: Terms such as MQL, incrementality or salience may be useful internally but can obscure the decision. Translate them into commercial language where possible.
Blaming the market: External conditions matter, but simply blaming the market does not explain management’s response. Show what changed and what marketing is doing about it.
Overclaiming attribution: If brand activity cannot be directly attributed to a specific revenue number, do not invent precision. Show the evidence and explain the role of the investment.
Treating the CFO as an opponent: Finance is often testing the assumptions behind the request. Bring finance into the process early enough to challenge the numbers before the board does.
The practical fix for all five is the same: make the assumptions, evidence and trade-offs visible before the meeting.
The read
Marketing budgets remain under pressure because boards have competing demands for cash, growth and efficiency. That pressure is unlikely to disappear simply because marketing produces a better presentation.
What needs to change is the quality of the evidence available before the presentation begins.
A strong budget defence is built through repeated board reporting, agreed measures, honest forecasts, visible long-term indicators and clear consequences for different investment levels. The meeting is simply where that record gets tested.
Do one thing this month: create a one-page version of your next budget defence and start reporting the same numbers now. Do not wait for budget season to introduce the argument.
For more practical analysis on brands, CMOs, marketing effectiveness and strategy, subscribe to the daily brief. Get the key developments and useful marketing thinking delivered to your inbox.
FAQ
1. How do CMOs justify marketing budget to a board?
CMOs justify marketing budget by connecting investment to agreed business outcomes, showing forecasts against actual results and explaining the consequences of different spending levels. The evidence should already be familiar to the board before budget season. A clear record of performance, assumptions and trade-offs is more useful than a one-off presentation.
2. What marketing metrics do boards actually care about?
Boards generally care about metrics that help them understand revenue, margin, cash and risk. The exact measures vary by business, but may include pipeline, acquisition economics, retention, revenue contribution, forecast accuracy and relevant brand indicators. Reach and impressions can provide context, but rarely answer the main investment question on their own.
3. How do you defend brand spend against performance spend?
Do not frame the discussion as brand versus performance. Show the different jobs each investment performs and the different time horizons involved. Performance activity can often be linked more directly to near-term outcomes, while brand work supports future demand, consideration and brand equity. Report both using appropriate evidence.
4. What should be on a one page board update?
A one-page board update should contain the business objective, performance against the agreed forecast, the proposed investment, key assumptions and the consequence of alternative budget levels. Keep supporting channel data, campaign detail and methodology in the appendix. The page should make the decision required from the board immediately clear.
5. How should you respond to a budget cut request?
Prepare tiered scenarios before the request arrives. For each level, show what will be removed, what will be protected, what outcome changes and when the effect is likely to appear. This turns a budget cut from a simple cost-saving exercise into a discussion about the commercial consequences of different choices.
6. When should budget defence work start?
Budget defence work should start well before the formal budget meeting. The most useful preparation is ongoing: agree the scorecard, establish forecasts, report actual results, track long-term indicators and document trade-offs throughout the year. By budget season, the board should recognise the numbers and understand the logic behind the request.